
Topic hub
Retirement Withdrawal Strategies
How should you take money out of your retirement pots? There’s no single best way. It depends on your other income, how much you can flex your spending and how you feel about market falls.
This page explains five of the main withdrawal strategies, compares them side by side and links to a calculator for each so you can test your own numbers.
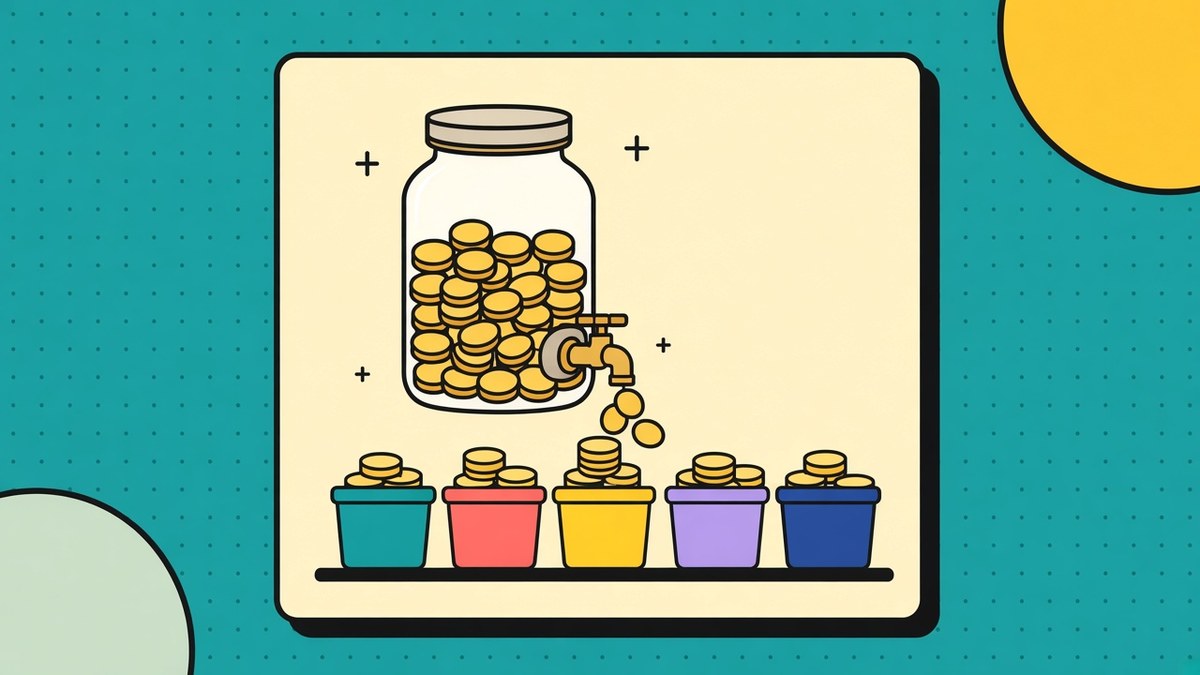
How to use this page
Start with the strategy that sounds closest to your situation, then put your own numbers into its calculator.
Change one assumption at a time and see what actually moves.
The five strategies
the 4% rule
Fixed percentage
Take a set percentage in year one, then adjust that amount with inflation.
dynamic spending
Guardrails
Agree raise, hold or cut rules in advance based on how the plan is tracking.
cash, bonds, growth
Bucket strategy
Keep near-term spending in cash, with longer-term money invested for growth.
essentials first
Floor and upside
Cover essential bills with State Pension, defined benefit pensions or annuity income, then keep the rest flexible.
which pot first
Tax-aware order
Decide which pot to draw from first across ISA, pension tax-free cash and taxable withdrawals.
Quick comparison
Facts drawn from the existing hub copy. Illustrative only, not advice.
| Strategy | Spending style | Responds to markets? | Main trade-off | Calculator |
|---|---|---|---|---|
| Fixed percentage | Set % in year one, then inflation-adjust | No automatic cut after a bad year | Simple, but rigid when markets fall | 4% rule |
| Guardrails | Raise, hold or cut by pre-agreed rules | Yes, when you cross the rails | Needs flexible discretionary spending | Guardrails |
| Buckets | Near-term cash, longer-term growth | Aims to avoid forced sales after a drop | More cash can mean less growth | Buckets |
| Floor and upside | Essentials from guaranteed income; rest flexible | Floor stays; upside can move | More guarantee can mean less flexibility | Drawdown vs annuity |
| Tax-aware order | Chooses which wrapper to draw from first | Tax-led, not market-led | Best order depends on the whole picture | Tax order |
More tools
Related calculators if you want to push a plan harder once you have a starting approach.
Related guides
Pensions
Why pension calculators give different answers
See how inflation, fees, retirement age and tax change the result.
Retirement timing
Can You Retire Before Your Partner?
Cover the gap while one salary carries on, then check both of you retired.
Early retirement
Can I retire at 55?
A worked example for funding the pension gap and comparing options.
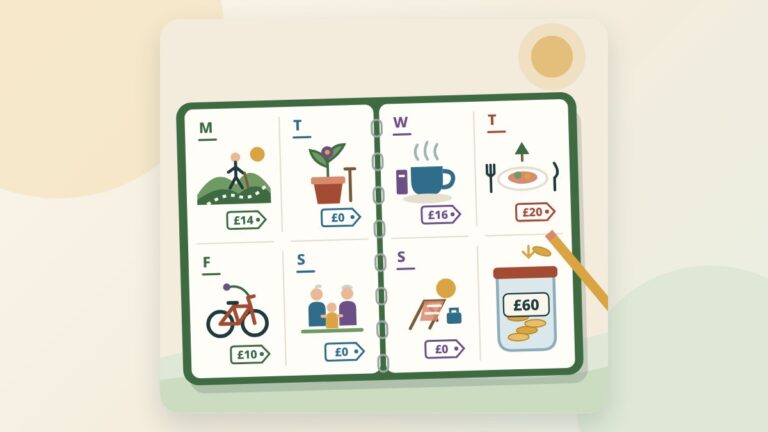
Spending
What would your ideal retirement week cost?
Build a retirement budget from the week you want, then test it.
Want the whole plan in one place?
Plan Hub brings your pots, spending and State Pension timing together so you can test a withdrawal path against the rest of the plan.
See Plan HubFAQs
What is a retirement withdrawal strategy?
It is your plan for how and when you take money from pensions, ISAs and other savings once you start using them to fund your lifestyle.
The strategy can cover how much you withdraw, which accounts you use and whether your spending changes when markets rise or fall.
What is the 4% rule in the UK?
The 4% rule is a simple withdrawal approach.
The traditional version starts by withdrawing around 4% of the original retirement pot in year one and then adjusting that amount for inflation.
It came from US retirement research, so it should not be treated as a guaranteed UK retirement income.
Use The 4% Rule Calculator to test the idea with your own numbers.
What are guardrails withdrawals?
Guardrails allow retirement spending to change depending on how your investments are performing.
You set upper and lower limits in advance. If your plan moves beyond them, the rules tell you when spending can increase, stay where it is or needs to fall.
Use the Guardrails Withdrawal Strategy Calculator to see how this works.
What is a bucket strategy?
A bucket strategy separates retirement money according to when you expect to spend it.
You might keep near-term spending in cash, money for the middle years in lower-risk assets and longer-term money invested for growth.
Use the Bucket Strategy Calculator to try different cash, bond and growth allocations.
What does floor and upside mean?
Floor and upside separates essential spending from flexible spending.
State Pension, defined benefit pensions or annuity income can form the floor that helps cover essential bills.
Money remaining in pension drawdown, ISAs or other investments provides the upside for spending that can change.
Use the Pension Drawdown vs Annuity Calculator and Retirement Income Calculator to explore the two sides.
Which pot should I take money from first?
There is no withdrawal order that is automatically right for everyone.
One approach might use ISA money first, then pension tax-free cash and then taxable pension withdrawals. But other income, tax rates, investment accounts, inheritance plans and your partner’s finances can all change the result.
Use the Retirement Withdrawal Strategy Calculator to compare different sequences.
What is a safe withdrawal rate?
A safe withdrawal rate is an attempt to estimate how much you might withdraw from a portfolio without exhausting it over a particular retirement period under the assumptions being tested.
“Safe” does not mean guaranteed.
Use the Safe Withdrawal Rate Stress Tester and Probability of Running Out of Money Calculator to test the idea under less comfortable scenarios.
How do I bridge to State Pension?
If you stop work before your State Pension starts, you need another way to fund those years.
That could mean drawing more heavily from ISAs, cash or private pensions during the gap, before your State Pension later reduces the amount you need from those pots.
Use the Retirement Drawdown Planner for the withdrawal path, or the Can I Retire Calculator for a wider affordability check.
Why was so much tax taken from my first pension withdrawal?
Flexible pension withdrawals are normally processed through PAYE.
If the provider does not yet have an appropriate tax code, your first payment can sometimes have more tax deducted than you expected.
That does not necessarily mean the final amount of tax due will be that high.
Use the Emergency Tax Calculator to understand what may have happened and explore the figures.

